September is the worst time to order mattresses from China because Christmas-season orders, the domestic “Golden September” sales rush, and Canton Fair stocking all collide in the same four-week window—factories don’t need your order, and both your price and your lead time lose all negotiating room. April is the best time because the line is stable after Chinese New Year, Christmas shipments are already delivered, and new fair-season orders haven’t landed yet. January is a near-tie with September due to CNY capacity shutdowns. The strategy: stop asking “how good is this factory” and start asking “when am I placing this order.” Your timing is a negotiation chip most buyers never use.
Every overseas buyer who has sourced mattresses from China for more than two seasons has lived the same confusion. The same factory quoted you 25 days in March and 55 days in October. The same PO that sailed smoothly last year is now “in queue” with no ship date. Your sales team is asking why inventory is late; your factory’s sales rep is politely non-committal; and somewhere in that gap, you are losing retail shelf space or e-commerce ranking.
The instinct is to blame the factory. After ten years walking production floors in Foshan, Dongguan, Nantong, and Anji, I can tell you the truth is less personal and more structural: you are not competing with the factory. You are competing with the orders queued in front of yours. And the length of that queue changes every month of the year. Understanding that rhythm—rather than switching factories every time you’re disappointed—is the difference between buyers who get 25-day lead times at normal prices and buyers who pay rush premiums for 60-day chaos.
The Core Logic: Order Timing Is Negotiating Leverage
A mattress factory’s capacity is not a fixed number. It is a queue. The queue is longest when three demand streams peak simultaneously, and it is shortest in the gaps between them. When the queue is long, the factory holds all the leverage: your order is small relative to the Christmas containers ahead of it, your requests for priority get politely declined, and any price discussion is met with “material costs are up this quarter.” When the queue is short, leverage flips. Factory sales reps start calling you. Slot openings appear. Prices soften, not because the mattress is cheaper to make, but because a filled production line this week is worth more to the factory than a theoretical margin point.
This is the best time order mattress China strategy that experienced importers quietly practice: they don’t chase the lowest quote. They chase the emptiest queue.
Definition: The Capacity Gap and the Production Window
Two terms run through this entire article, so let me define them precisely, the way a production planner would.
The capacity gap is the structural difference between a factory’s available monthly capacity and its confirmed order backlog at a given point in time. A large capacity gap means open slots, negotiable prices, and genuine priority for your order. A zero or negative capacity gap means your PO joins a queue and waits its turn regardless of what the contract says.
The production window is the calendar period—typically measured in weeks—during which placing an order reliably converts into that short-queue treatment. In China’s mattress industry, the two dominant production windows are the post-CNY stabilization period (roughly late February through May) and, more reliably, April specifically, which sits between the Christmas delivery cycle and the autumn order surge.
The Full-Year Mattress Ordering Calendar
The calendar below reflects conventional rhythms observed across major mattress manufacturing regions. Exact dates shift each year and are subject to verification against current factory schedules, raw material cycles, and holiday timing.
| Month | Queue Status | Mattress Lead Time (conventional range) | Negotiating Position | Verdict |
|---|---|---|---|---|
| January | Collapsing pre-CNY | 45–70 days, then lines shut | None—factories ration slots | Avoid |
| February | CNY shutdown + restart | Minimal output; quality variance risk | Weak until lines stabilize | Transition only |
| March | Lines stabilizing, slots opening | 30–40 days | Improving weekly | Acceptable |
| April | Shortest queue of the year | 20–30 days | Strongest buyer leverage | Best month |
| May | Fair-season new orders arriving | 25–35 days | Still favorable | Very good |
| June | Steady, pre-peak buildup | 30–40 days | Neutral | Acceptable |
| July | Christmas orders beginning to stack | 35–45 days | Neutral to weakening | Plan carefully |
| August | Peak-season congestion forming | 40–55 days | Factory-favored | Risky |
| September | Maximum congestion | 55–75 days | No leverage | Worst month |
| October | Post-fair surge continues | 50–70 days | Weak | Poor |
| November | Christmas deadline hard cutoff | 45–65 days + expedite premiums | Weak but urgent | Poor |
| December | Queue drains toward Christmas cutoff | 35–50 days | Recovering | Acceptable |
One pattern deserves emphasis: the mattress lead time you are quoted is not one number. It is the same mattress, the same line, at different points in the queue.
Why September Is the Worst Month: Three Demand Streams Collide
September’s congestion is not one cause. It is a stack of causes arriving in the same month, each one individually manageable, together forming the worst month mattress production faces all year.
| Congestion Driver | What Happens in September | Effect on Your Order |
|---|---|---|
| Christmas-season order cutoff | Factories freeze Q4 shipping deadlines; late POs get pushed | Your container misses retail shelf dates |
| Domestic “Golden September, Silver October” | China’s own retail peak pulls capacity inward | Export slots deprioritized |
| Canton Fair pre-stocking | Exhibitors and repeat buyers front-load orders | Factory quotes harden, slots vanish |
| School-year & holiday retail resets | Importers restock for year-end promotions | Queue length compounds |
| Golden Week holiday (Oct 1–7) | Factories compress September output to pre-ship | Effective capacity shrinks further |
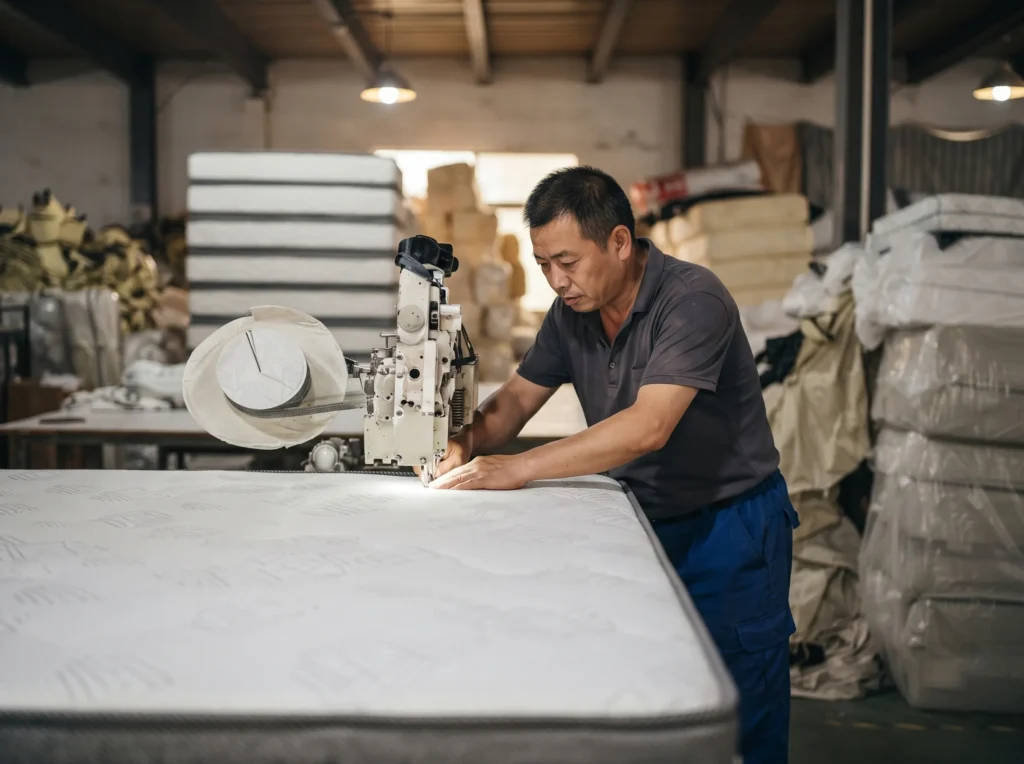
Here is the part buyers find hard to accept: in September, the factory is not being difficult with you. The Christmas program for a major retail chain—thousands of units, contracted months in advance, with penalty clauses—simply outranks your container. The factory is not choosing against you; the queue is choosing for it. Any sales rep promising you a 30-day turnaround in mid-September is either quoting a line they don’t have or planning to disappoint you politely in week six.
Why April Is the Best Month: The Structural Window
April’s advantage is equally structural, which is why it repeats almost every year. By mid-April, the Chinese New Year restart is fully complete—workers are back, new-hire training is done, and quality variance from the February restart has worked itself out. The Christmas order wave shipped in October and November, so those containers are not competing for line time. And the autumn surge has not begun; Canton Fair orders placed in April are still being negotiated, not yet scheduled.
The result is the widest capacity gap of the year. Factories in this window are not desperate, but they are hungry. They have payroll to cover and an export line that needs feeding before the Q3 crunch. That is when your 500-unit order matters to them, and when a sales rep has genuine room to move on price, free fabric upgrades, or a guaranteed slot. Buyers who place annual programs in April routinely report the year’s best terms without a hard negotiation at all—the leverage arrives automatically with the calendar.
September vs. April: The Core Comparison
| Dimension | April | September |
|---|---|---|
| Typical quoted lead time | 20–30 days | 55–75 days |
| Price flexibility | Genuine room to negotiate | Quotes harden; “materials up” reflex |
| Order priority for new buyers | High—factories chase volume | Low—Christmas programs dominate |
| Slot availability | Open, bookable | Rationed, waitlisted |
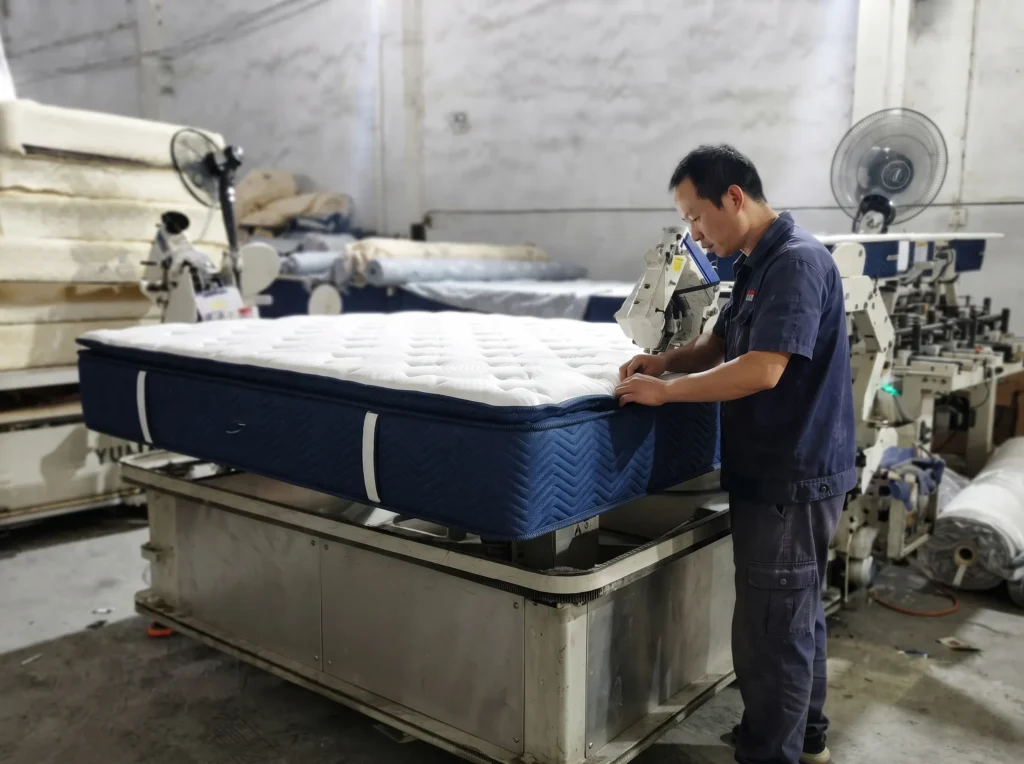
| Quality stability | Lines stable post-CNY | Overtime shifts raise variance risk |
| Your leverage | Maximum | Near zero |
| Biggest risk | None structural | Missing Christmas retail windows |
Regional Rhythms: Nantong and the Other Belts
Not every production belt breathes at exactly the same pace, and the Nantong mattress season illustrates this well. Nantong’s cluster is heavily oriented toward mattress machinery, components, and OEM programs tied to large retail contracts—meaning its capacity is absorbed early by program business, and its April window is slightly narrower than Guangdong’s, which has more spot-order flexibility. Guangdong belts (Foshan, Dongguan, Guangzhou) run a more export-general rhythm; Anji and other upholstery-adjacent clusters feel the furniture fair cycle more acutely. All regional patterns below are conventional observations, subject to verification with individual factories.
| Region | Distinctive Seasonal Pattern | Practical Implication |
|---|---|---|
| Nantong | OEM program absorption; narrower April window | Book Nantong slots earlier—by March |
| Foshan / Guangdong | Most export-general rhythm; widest April gap | Latest acceptable cutoff before September crunch |
| Anji cluster | Upholstery fair cycle spillover | Avoid weeks adjacent to furniture fairs |
| Component suppliers (foam, springs) | Raw-material price cycles drive congestion | Lock material pricing when placing April POs |
The Risk Warnings: What Quietly Breaks a Well-Timed Order
Three risks deserve blunt treatment.
First, verbal peak-season promises. Anything a factory tells you in September about “we’ll squeeze you in” that is not written into the PO with a stated penalty structure is a courtesy, not a commitment. Get production slot dates in writing, with a defined consequence for missing them.
Second, logistics stacking. Even a factory that ships on time in October hands your cargo to a peak-season freight market—congested ports, rolled bookings, and rates that can erase your product margin. A September order problem is never just a production problem; it is a production problem plus a freight problem arriving together.
Third, raw-material volatility. Foam chemicals, steel for springs, and fabric prices move on their own cycles. A quote anchored in April’s stable input market is a genuinely better quote; a quote from September often embeds uncertainty premiums you are paying without knowing.
Peak-Season Contingency: If You Must Order During Congestion
Sometimes the calendar cannot be obeyed—a retail reset is immovable, a container was damaged, a new account lands in August. If you are ordering into congestion, mitigate rather than hope.
| Risk | Mitigation | Why It Works |
|---|---|---|
| Queue delay | Split order across two factories | One queue miss halves the damage |
| Slot loss | Pay deposit early; lock written slot dates | Money moves you from waitlist to schedule |
| Christmas deadline miss | Air-freight the top 10% SKU volume | Protects shelf presence while sea freight catches up |
| Quality variance from overtime | Pre-shipment inspection at 80% production | Catches drift before container stuffing |
| Freight rate spike | Book ocean freight at PO confirmation, not at readiness | Peak-season rates punish late bookers |
Playbook by Buyer Type
Importers and wholesalers should anchor annual programs in April, place top-up flexibility for June, and treat September as a reorder-freeze month. If a major account lands in Q3, split production across April-slotted and August-slotted capacity rather than forcing one queue.
E-commerce sellers running FBA or overseas warehouse models face ranking cliffs if stockouts hit. The rule is simple: your replenishment PO must leave the factory no later than June for Q4 selling. Ordering in September to fix an October stockout is buying a December arrival—plan the cycle backward from Prime-season inventory deadlines.
Hotel FF&E buyers have the most leverage of any group because their programs are large and their timelines are known years ahead. Sign the program in April, tie payments to slot dates, and insert a liquidated-damages clause. Hotels that negotiate in September routinely absorb both the longest lead times and the least favorable terms of any buyer category.
Individual and small-volume buyers feel the queue most brutally, because 20 units mean nothing to a factory in September. Your best month is May, when the April window is still partially open and smaller orders can still find line gaps. If you must buy in autumn, go through a consolidator who already holds April-priced, pre-booked slots.
Frequently Asked Questions
How long is the lead time if I order mattresses in September?
Conventionally 55 to 75 days from deposit to ex-factory, versus 20 to 30 days in April—before ocean freight is added. Complex builds (hybrids, pillow-top, custom fabrics) push the upper end. These are industry-convention ranges, subject to verification with your specific factory and year.
What is the latest I can order for Christmas-season retail?
Working backward: retail shelf reset typically needs goods in-country by early to mid-November. That means on-water by late September, ex-factory by early September at the absolute latest—which, as this calendar shows, is precisely the worst time to be placing the order. Experienced importers lock Christmas programs in April or May, not September.
How much cheaper is April ordering, realistically?
Factories rarely hand you an explicit “April discount.” The savings arrive as softer unit pricing on negotiation, waived surcharges, free material upgrades, priority slot guarantees without rush fees, and—most valuable—zero expedite premiums when something goes wrong. Buyers who compare their April and September landed costs on identical specs routinely find 5–12% all-in differences; exact figures are subject to verification against your own order history.
Does Nantong’s mattress season differ from Guangdong’s?
Yes, modestly. Nantong’s cluster leans toward OEM programs and machinery-adjacent production, so its capacity is absorbed earlier and its April window is somewhat narrower. Guangdong belts offer more spot-order flexibility deeper into May and June. The safest approach is to pull Nantong slot bookings into March while using April–May for Guangdong programs.
I already ordered in peak season. What can I do now?
Act on the four levers that don’t require factory generosity: split remaining volume to a second factory with open slots, convert part of the order to a faster-build spec, pre-book ocean freight immediately rather than at readiness, and schedule a pre-shipment inspection so you don’t compound delay with a quality rejection. And for next year: calendar the April window now, while this year’s pain is still legible.
Your Turn
Pull up your last three mattress POs and check the order month against the delivery outcome. Did the September order run long? Did the spring order sail clean? Tell us your pattern in the comments—your real lead-time data is worth more to other buyers than any calendar I can publish.
Recommended Resource
Interi Furniture specializes in custom furniture manufacturing for residential, hospitality, and commercial projects. Their experience in materials, craftsmanship, and project realization makes them a valuable resource for designers and buyers seeking tailored furniture solutions from China.